
Exit planning for owner-managed businesses
Most owner-managers sell a business once. The gap between an acceptable outcome and an excellent one is usually decided long before a buyer opens a set of accounts, in the eighteen months to three years when the business can still be shaped rather than merely presented.
We work with UK owner-managed and mid-market businesses inside that window. Typically £500k to £5m of EBITDA, five to 150 employees, and a founder who has begun to think seriously about what comes next without yet committing to a timetable.
What a buyer prices, and what a buyer discounts
Every acquirer runs the same underlying assessment, whether they are a trade buyer, a private equity investor or your own management team. They are pricing sustainable earnings, the credibility of the evidence behind those earnings, and the risk that the business changes character the moment you stop turning up.
What gets discounted is predictable and, in our experience, consistent across sectors:
Customer concentration, particularly where the largest relationships are personally held by the founder.
Owner dependency, where operational knowledge, pricing authority or key relationships sit with one person.
Earnings that cannot be evidenced, or that require explanation before they can be understood.
A management team with a visible gap where the second tier should be.
A growth story that depends on the founder remaining in place to deliver it.
None of these are fixed at the point of sale. All of them are fixable given time, which is the entire argument for starting early.
The window that decides your multiple
Preparation is not a single exercise. What is available to you depends almost entirely on how much runway remains:
Three years out, structural change is possible. Customer mix, pricing architecture, contract terms and the recruitment of a genuine second tier are all still in play.
Eighteen months out, financial track record can still be built. Two clean, consistent years of reported performance is a materially different asset to one.
Six months out, the work is presentation, data room preparation, narrative and diligence readiness. This protects value rather than creating it.
Inside three months, you are managing a process rather than shaping an outcome.
How we prepare a business for sale
Every engagement starts with establishing what the business is worth today and, more usefully, what specifically constrains that number. From there the work usually covers:
Strengthening baseline financial performance, so the earnings a buyer capitalises are both as high and as defensible as they can be.
Building management depth, so the business demonstrably runs without you. This is the single largest driver of key-person discount and the slowest to fix.
Evidencing the numbers through management accounts, KPI reporting and forecasting that survive third-party scrutiny rather than inviting more of it.
Constructing the commercial narrative: why this business, why now, and where the next phase of growth comes from for the buyer rather than for you.
Mapping the realistic buyer universe, because a trade acquirer, a private equity platform, an existing platform seeking a bolt-on and a management team each value very different things.
What preparation is worth
Value creation planning of this kind targets an uplift of one to two times on the EBITDA multiple achieved. Structured preparation also removes roughly a quarter of the elapsed time between accepted offer and completion, largely because the questions a buyer would otherwise ask during diligence have already been answered.
The less obvious return is optionality. A business that is genuinely ready to sell is also a business that can decline to sell, accept a partial exit, take investment instead, or wait another two years for a better market. Preparation converts a single available outcome into a choice between several.
Recent work
Luxury holiday rentals: a five-year business plan, management team assessment and succession plan, a single KPI framework and a shortlist of bolt-on acquisition targets, several years ahead of an exit or funding event.
Professional services: a buy and build strategy and the capital options for a fast-growing firm, positioning it for a private equity partnership and an eventual exit.
Senior advisers, no associate layers
Every Bayside engagement is led by one of our co-founders, Sam Miller or Stephen Murray. There are no handoffs and no associate layer between you and the person doing the thinking. Between them they have raised over £200m of capital, completed more than 50 transactions with a largest single deal of £100m, and held over 20 board positions. Both have sat on all sides of the table as investors, advisers and operators.
Common Questions
When should I start exit planning? Ideally two to three years before you intend to sell, and at minimum eighteen months. The earlier you start, the more of the value drivers remain within your control rather than the buyer's.
What size of business do you work with? Typically UK owner-managed and mid-market businesses with EBITDA between £500k and £5m and between five and 150 employees. We work UK-wide, with most of our deal flow originating in the Midlands.
Do you also run the sale process itself? Yes. We support bilateral sales and structured processes, and we can work alongside your existing corporate finance adviser or lawyer where one is already appointed.
How is this different from what my accountant does? Your accountant reports what has happened and manages compliance. Exit planning is concerned with what a buyer will pay and why, and with changing the business in advance so that number is higher and more certain.
What does the first conversation cost? Nothing. The first conversation is free, carries no obligation, and is strictly confidential.
Sector Insights
See our thoughts on Exit Planning in the following sectors within our Insights pages:
Further reading: The Exit Readiness Audit - 20 questions that score your business the way a private equity buyer would.
Related services
Management Team Strengthening- because management depth is usually the longest lead-time item in exit preparation
Financial Readiness & Modelling - for the reporting and forecasting a buyer will test
Bilateral Sale Support - if a buyer has already approached you
Planning an exit or looking to increase the value of your business?
Contact Sam Miller or Stephen Murray directly for an initial confidential discussion.
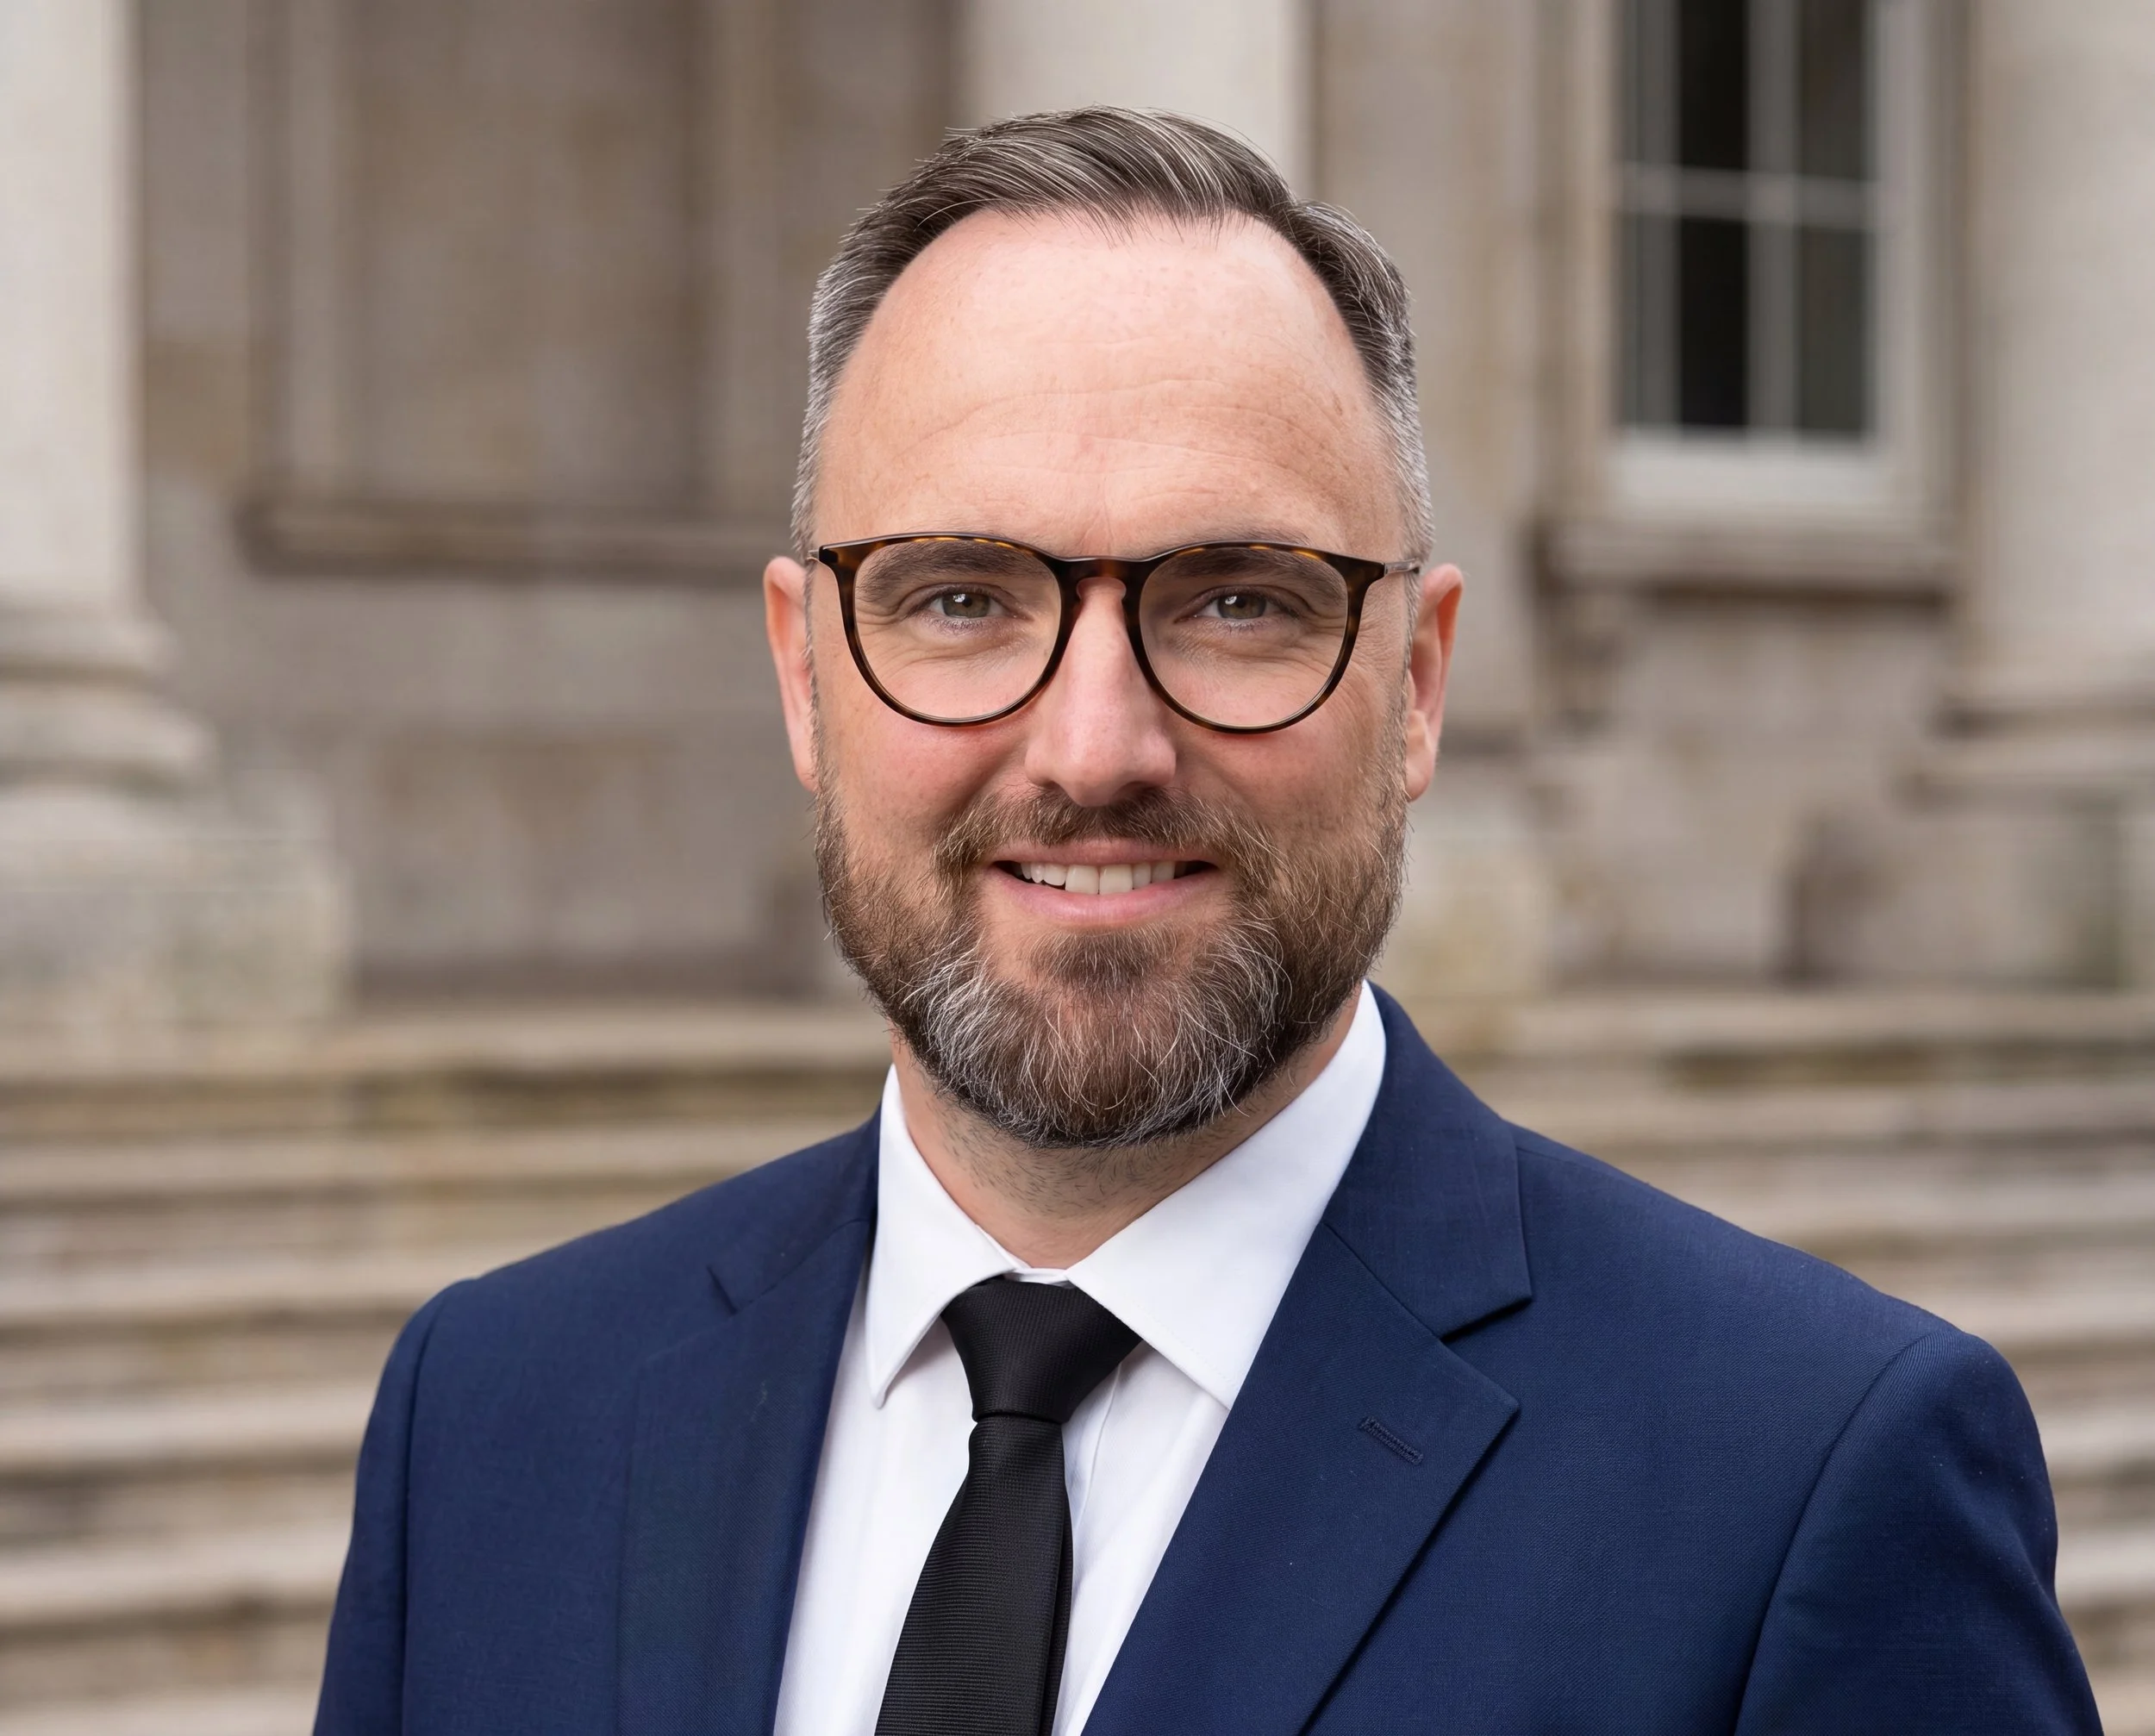
Sam Miller
Co-Founder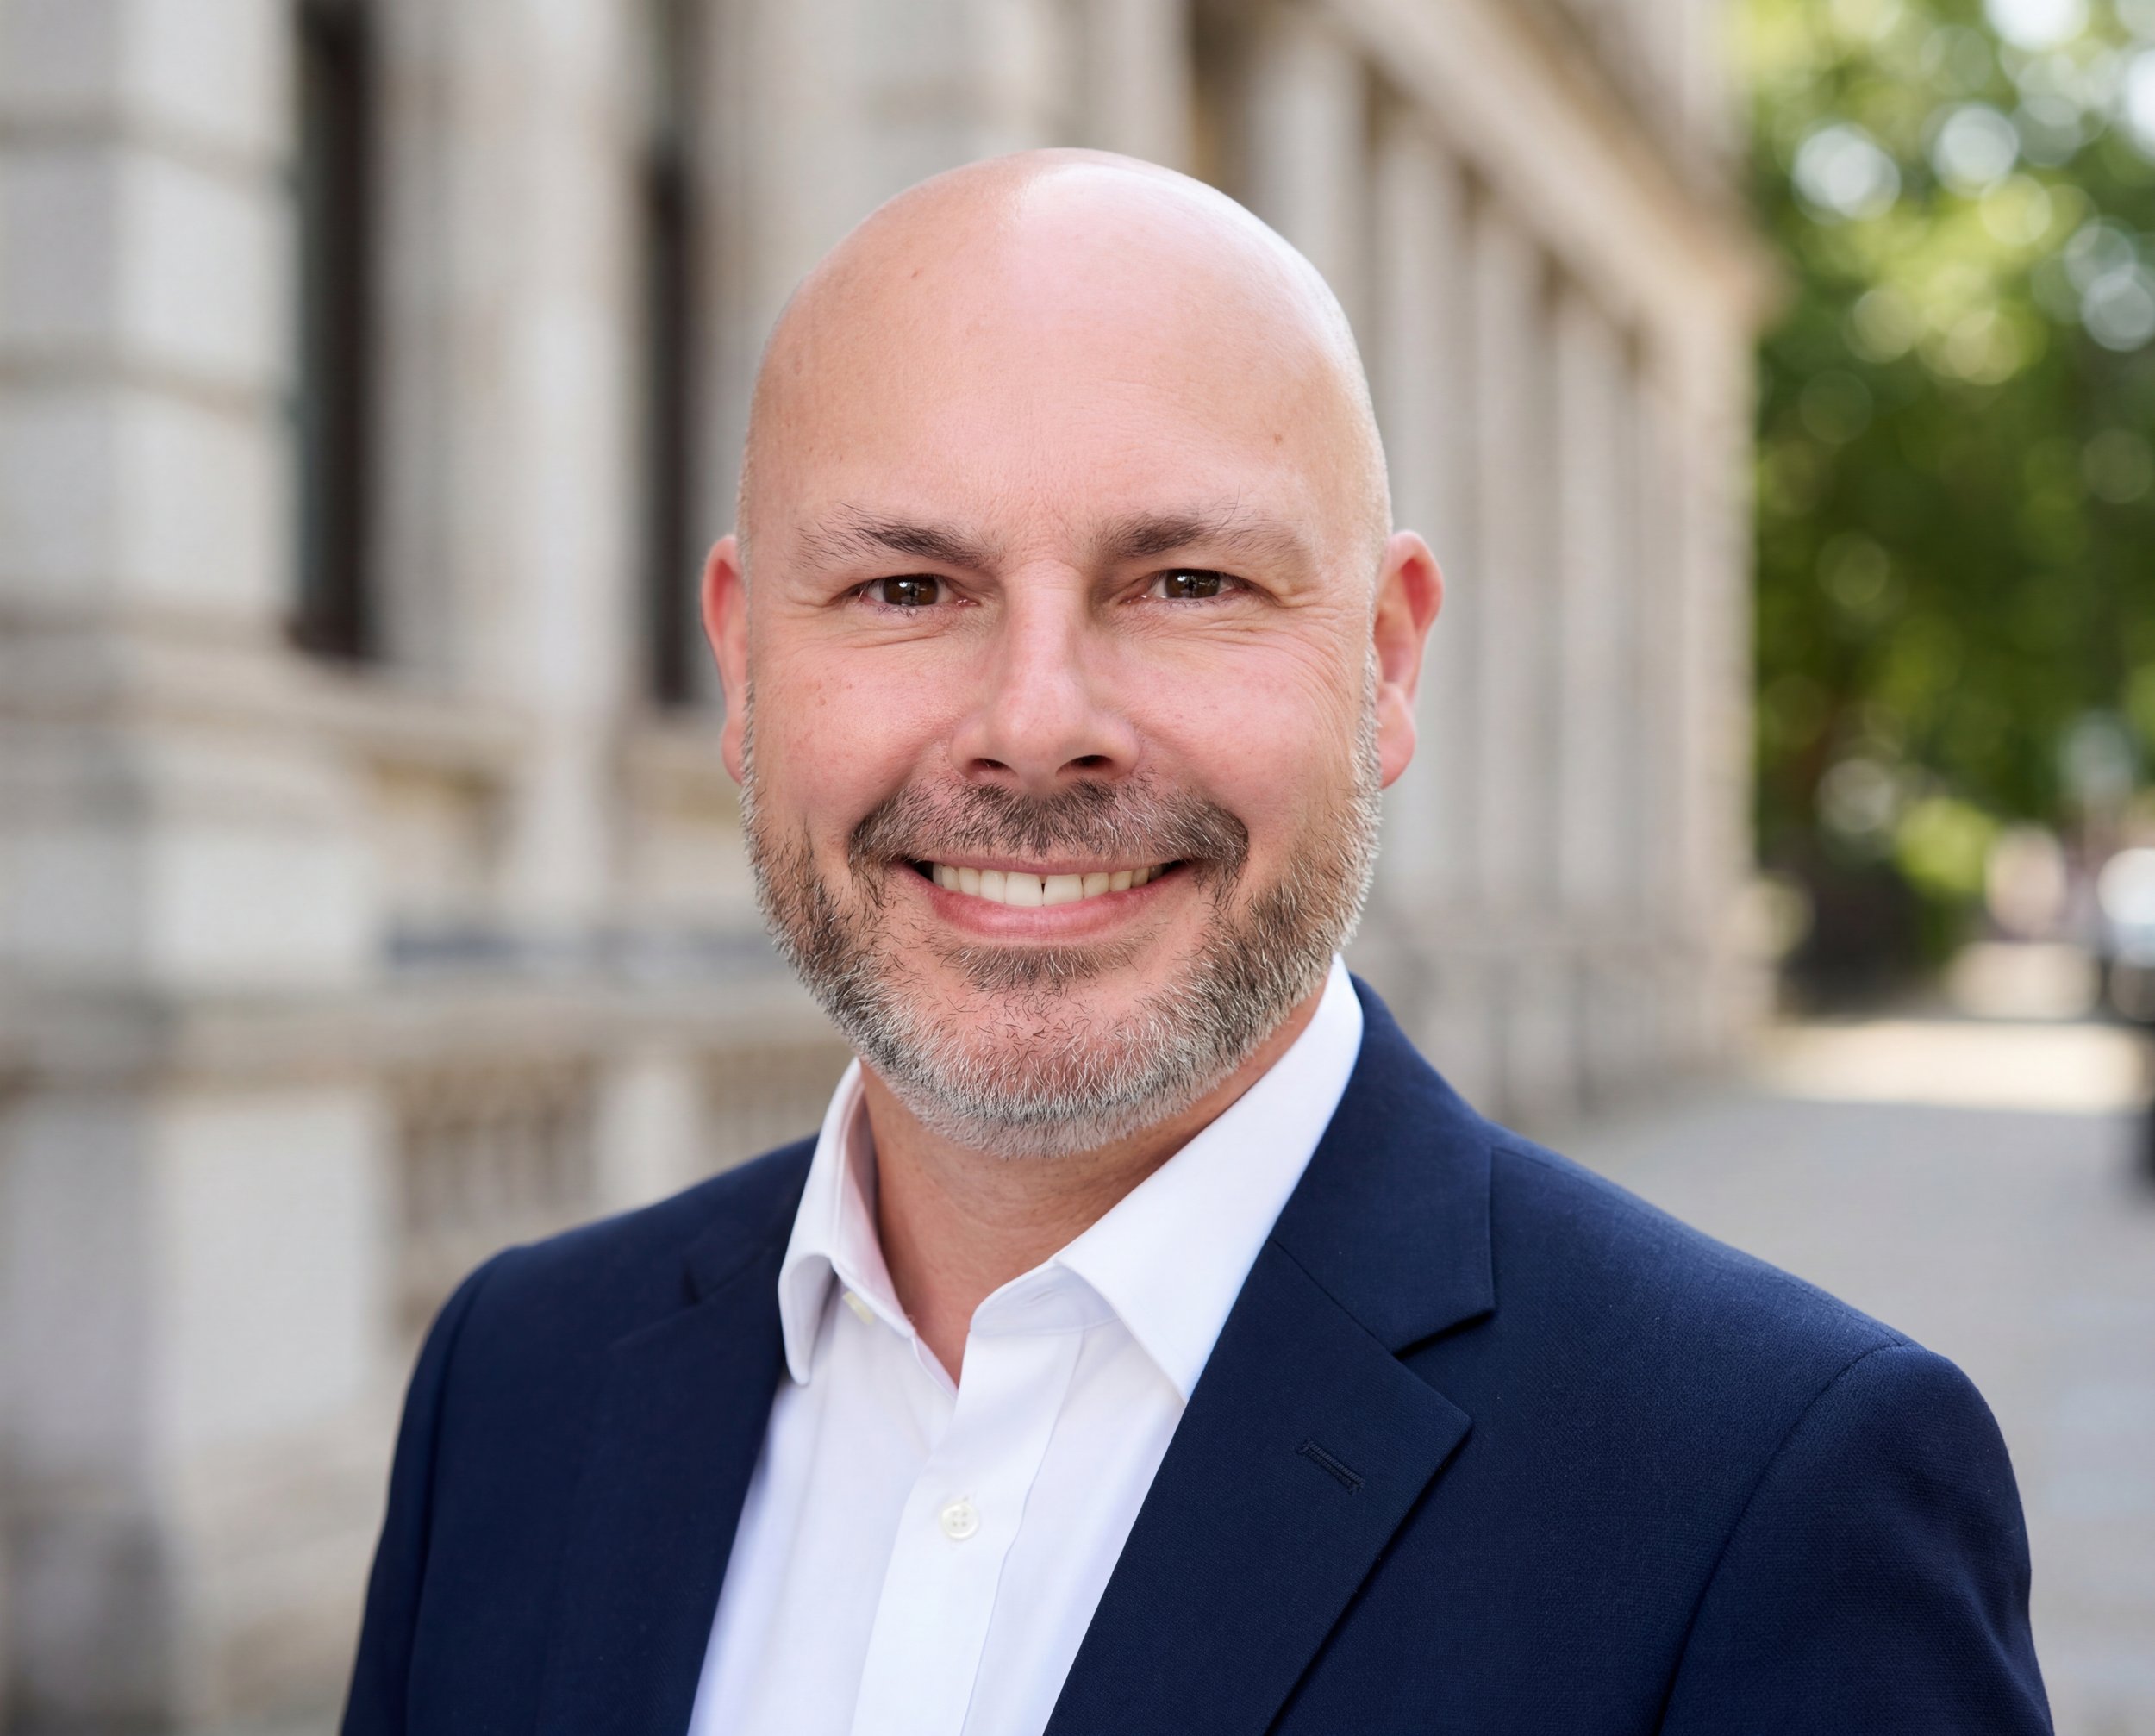
Co-Founder